Credit card debt is draining you: why personal loans are taking over
Credit card debt is draining you at 22%+ APR. See how personal loans cut costs, what rates look like after the Fed hike, and when to switch.
Warning: minimum payments keep you broke
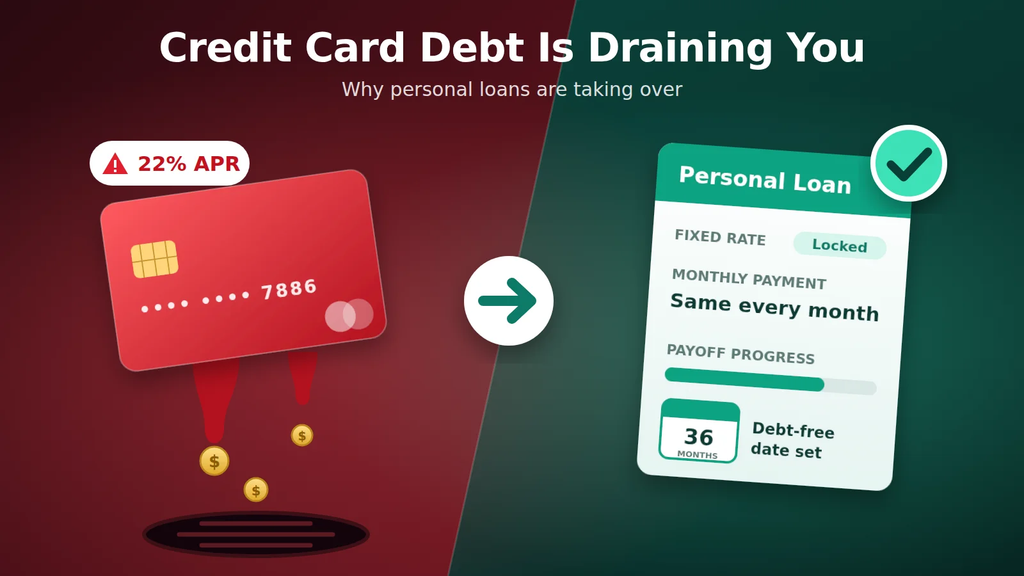
Credit card debt is draining you, and it’s not just in your head.
If you opened your September statement and saw back-to-school charges on top of a balance that never seems to shrink, you’re in good company.
Americans now owe $1.263 trillion on credit cards, according to the Federal Reserve Bank of New York.
The result: millions of borrowers are quietly moving their card balances into personal loans.
These loans have fixed rates, fixed payments and a real end date. Here’s why it’s happening, what the numbers say, and how to tell if it makes sense for you.
H2: Why Credit Card Debt Is Draining You Right Now
The Federal Reserve’s latest data shows the average APR on credit card accounts that pay interest is 22.15%.Rates also depend on your credit. WalletHub puts new offers at 27.01% for fair credit and 23.27% for good credit.
At 22.15%, an average balance of $7,886 costs you about $146 a month in interest alone. That’s money that never touches your balance.
The September Fed hike makes it worse
The FOMC voted 12–0 to raise the federal funds rate to 3.75%–4.00%.
Fed Chair Kevin Warsh said that “inflation is too high, and has been for too long.” Inflation is running at 3.4%, and 16 of 18 officials expect at least one more hike before year-end.
Most cards have a variable APR tied to the prime rate, so this hits you directly.
Ted Rossman, former principal analyst at Bankrate, explains that Fed rate changes “generally pass through to customers within a month or two” and affect both new and existing balances.
Back-to-school bills just landed
August spending is now showing up on September statements. A NerdWallet survey found that 19% of parents expected to go into credit card debt for back-to-school shopping, and 24% planned to use Buy Now, Pay Later.
More people are falling behind
The New York Fed reports that the share of card balances moving into serious delinquency (90+ days) reached 6.97% in Q2 2026.
Joelle Scally, Economic Policy Advisor at the NY Fed, warned that “new delinquencies for auto loans and credit cards remain at elevated levels”.
How Much Can You Save by Switching?
Does consolidation help your credit score?
It can. A TransUnion study found that 68% of consumers who consolidated saw their credit scores rise by more than 20 points.
Average card balances dropped from $14,015 to $5,855. “Debt consolidation loans generally appear to do what they’re designed to do,” said Liz Pagel, then SVP at TransUnion.
H2: Is a Personal Loan Right for You?
A personal loan makes sense if
- Your new loan APR is clearly lower than your card APR, fees included;
- You can afford the fixed monthly payment comfortably;
- You’re committed to not running your cards back up after paying them off;
- Your credit score is 690 or higher, which puts you in the better rate tiers.
Watch out for these risks
- Origination fees: some lenders deduct them from your loan, so compare the APR, not just the interest rate;
- Fair or bad credit: average rates of 23.73% to 27.27% may not beat your card;
- Rising delinquencies: personal loan delinquency (60+ days) climbed to 3.81%. Borrow only what you can repay;
- Don’t count on a rate cap: the proposed 10% credit card interest cap is not law. Waiting for it could cost you months of interest.
How to Switch From Credit Card Debt to a Personal Loan in 5 Steps
Step 1: List Every Card Balance and APR
Before you talk to any lender, you need to know exactly what you owe and what it’s costing you. Pull up your most recent statement for every card and write down:
Look for the “Interest Charge” line on each statement. That’s the money you pay every month without reducing your balance by a single cent.
The average balance is $7,886, and the average APR is 22.15%. At those numbers, the interest comes to about $146 a month.
Step 2: Check Your Credit Score for Free
Your credit score is the single biggest factor in the rate you’ll get. The difference between tiers is huge:
| Credit Rating | Score Range | Average Personal Loan APR |
|---|---|---|
| Excellent | 720–850 | 15.02% |
| Good | 690–719 | 19.55% |
| Fair | 630–689 | 23.73% |
| Bad | 300–629 | 27.27% |
Source: NerdWallet, September 2026.
You can see your score for free through most banks and card issuers.
For your full reports, go to AnnualCreditReport.com, the official site that gives you free weekly reports from Equifax, Experian and TransUnion.
Step 3: Prequalify With at Least 3 Lenders
Prequalifying shows you your likely rate, loan amount and monthly payment without hurting your credit score, because lenders only do a soft credit pull.
A hard inquiry happens only when you submit a formal application.
Compare at least one lender from each category:
- Online lenders: fast decisions, often with funding in days, and easy online prequalification;
- Banks: may offer lower rates if you’re already a customer. The Fed reports 11.86% as the average on 24-month bank personal loans;
- Credit unions: federal credit unions are generally limited to an 18% APR ceiling. That makes them a strong option if your credit isn’t perfect.
Pro tip: look for lenders that offer “direct pay to creditors.” They send the money straight to your card issuers, so the cash never passes through your checking account.
Step 4: Compare APR, Fees and Total Cost
The rate in the ad is rarely the full story. Compare offers on these points:
- APR, not just the interest rate: APR includes origination fees, so it shows the true yearly cost;
- Origination fee: some lenders take it out of your loan up front. Example: with a 5% fee, you’d have to borrow about $8,301 to actually receive $7,886 to pay off your cards;
- Loan term: a longer term lowers your payment but raises your total cost;
- Prepayment penalty: make sure you can pay the loan off early without extra charges.
Here’s how the term changes the cost of the same $7,886 at 19.55% APR:
H3: Step 5: Pay Off the Cards Immediately and Set Up Autopay
Once the loan is approved and funded, act the same day:
- Pay every card balance in full. If your lender offered direct pay, confirm the payments went through;
- Check each card account a few days later to confirm a $0 balance. Interest charged in the last cycle can leave a small leftover amount;
- Set up autopay on the new loan so you never miss a payment. Some lenders also give a small rate discount for autopay;
- Keep your card accounts open. Closing them can hurt your score by increasing your credit utilization and shortening your credit history.
Once the cards are paid off, your credit utilization drops, which is one of the fastest ways to raise your score.
A TransUnion study found that 68% of consumers who consolidated saw their scores go up by more than 20 points.
Step 6: Protect Your Progress So the Debt Doesn’t Come Back
This is where most people slip. Paying off the cards with a loan only works if the cards stay at zero.
Otherwise you end up with double the debt.
- Take your cards out of your wallet and remove saved cards from online stores and apps;
- Plan ahead for the holidays. Holiday shopping is weeks away, so set a cash budget now, before the season starts;
- Build a small emergency fund, even $500 to $1,000. Most people rack up card debt again because of an unexpected expense, like a car repair or a medical bill;
- Turn on spending alerts in your card apps so any new charge shows up right away;
- Use your cards for one small bill only, such as a streaming service on autopay. That keeps the account active without letting a balance build up.
Author’s Opinion
After more than a decade covering personal finance, I can say this moment is different.
We have record-high card balances, APRs above 22%, and a Fed that just raised rates instead of cutting them.
Families who carry a balance are being squeezed from every side. I’ve watched too many readers wait for rates to drop or for a cap from Washington. Meanwhile, their interest charges quietly ate hundreds of dollars a month.
A personal loan isn’t magic, and it’s not for everyone. If your credit is fair or poor, the math may not work, and a counselor may be a better first call.
But if you qualify for a meaningfully lower fixed rate, locking it in before the next hike is one of the smartest moves you can make this fall.
Recommended Content
Your flood coverage might expire this month
Learn what happens after a lapse, how the NFIP renewal period works and what to check before.
Continue reading * You will remain on the current website